Showing posts with label lake norman. Show all posts

Monday, April 8, 2024

Huntersville|Lake Norman|Charlotte | A Seller’s duty to disclose latent material Defects

 QUESTION: In reading last week’s Q&A (Disclosure, Material Facts, the Residential Property Disclosure Statement, and the Due Diligence Fee, release date: 6/4/2020), I was surprised to learn that a seller has a legal duty to disclose a material defect about their property when the seller knows about the defect and the defect is one that is not discoverable by the buyer in the exercise of reasonable diligence. I have long understood that a seller can’t hide or actively misrepresent a material fact about their property, but I didn’t know that a seller has a duty to disclose latent material defects. Can you give me a real-life example of when a seller got into trouble for not disclosing a material defect?

ANSWER: Yes. The case of Everts v. Parkinson was decided by the North Carolina Court of Appeals in 2001. It involved the sale of a house in Wilmington in 1993 that was clad with synthetic stucco. Approximately two years after moving into the house in 1988, one of the owners, Mr. Parkinson, began to discover rotting pieces of brick molding around at least seven windows or doors. He replaced the rotting brick molding himself. Later, a painter who power-washed the house discovered that one of the windows was rotted in the sash, jamb, and part of the sill. Again, Mr. Parkinson made the repairs himself. He testified that the work “didn’t appear that complicated,” but an engineer who inspected the house testified that the window had undergone extensive repair behind the surface cladding between the inner and outer walls.

Mr. Parkinson later hired a company to build a band of stucco around the perimeter of each window to protect the windows from water. The president of the company testified that he told Mr. Parkinson the bands would not provide any waterproofing and that all the company was providing was decorative banding.

At the time of sale, the Parkinsons did not inform the buyers, Mr. and Mrs. Everts, about any of the repair work that Mr. Parkinson had done or about the construction of the stucco bands. The Everts’ home inspector testified that he did not observe any problems with the windows or doors and that he was not able to observe the perimeter joints of the exterior windows because they were concealed by the stucco bands. He also testified that he had not been informed of any moisture intrusion problems, and that if he had, he would have performed an intrusive test by inserting a moisture probe into the synthetic stucco. According to the inspector, it was not the normal practice of his company to perform this kind of test unless it was provided with information about water intrusion problems.

In its opinion, the Court of Appeals stated that “[a] duty to disclose material facts arises where material facts are accessible to the [seller] only, and he knows them not to be within the reach of the diligent attention, observation and judgment of the purchaser.” The Court concluded that a jury could infer from the evidence that material defects were known to Mr. Parkinson, that he knew the Everts’ were not aware of the defects and would not discover them in the exercise of diligent attention or observation, that Mr. Parkinson therefore had a duty to disclose the existence of the defects to the Everts’, and that his failure to do so supported their claim of fraud.

Monday, January 29, 2024

Huntersville | Lake Norman - Duty of Good Faith and Disclosure of Material Facts


Know Your Rights

QUESTION: Closing is two weeks away, and my buyer needs to sell their existing home in order to obtain a loan and close. Today we received notice that the buyer of my client’s home is terminating. My client is freaking out and demanding that I do not tell the seller about the termination. My buyer is also debating whether to inform the seller next week that if my client does not receive a refund of their Due Diligence Fee, they will delay terminating the current transaction all the way through the grace period in the contract. What do I do?

ANSWER: You need to immediately disclose to the seller or listing agent that your client may not be able to close. You also need to inform your client to seek legal counsel regarding the potential negotiation of the Due Diligence Fee.

The North Carolina Real Estate Commission has long instructed that a principal’s ability to complete a transaction is a material fact. This category of material fact “includes any fact that might adversely affect the ability of a principal (seller or buyer) to consummate the transaction such as: [1] a buyer’s inability to qualify for a loan, [2] a buyer’s inability to close on a home without selling a currently owned home, or [3] a seller’s inability to convey clear title due to the commencement of a foreclosure sale or judgment lien on the property.” 2022-2023 General Update Course, Section 1, Material Facts: Speak Up! Failure to disclose a material fact is the number one reason why agents are disciplined by the Commission. Here, your client’s likely inability to close is clearly a material fact that must be disclosed to the listing agent regardless of your client’s direction to the contrary.

As for the strategy to obtain a refund of the Due Diligence Fee, your client needs to be informed by legal counsel that every contract has an implied duty of good faith and fair dealing. North Carolina Courts have “consistently held that [i]t is a basic principle of contract law that a party who enters into an enforceable contract is required to act in good faith and to make reasonable efforts to perform his obligations under the agreement.” Blondell v. Ahmed (NC Court of Appeals 2016). Here, it sounds like your client may attempt to violate that duty in an attempt to obtain a refund of the Due Diligence Fee. Assisting your client in this endeavor may expose you to liability and violate both the License Law and the Code of Ethics. As such, it would be best to strongly advise them to use legal counsel in order to negotiate a termination of the transaction.

© Copyright 2023. North Carolina Association of REALTORS®, Inc.

This article is intended solely for the benefit of NC REALTORS® members, who may reproduce and distribute it to other NC REALTORS® members and their clients, provided it is reproduced in its entirety without any change to its format or content, including disclaimer and copyright notice, and provided that any such reproduction is not intended for monetary gain. Any unauthorized reproduction, use or distribution is prohibited.

Monday, June 19, 2023

I don't really need an experienced Realtor. I can just hire a friend?


I don't really need an experienced Realtor. I can just hire a friend?

Would you hire a law student to represent you in monetary litigation or hire an experienced lawyer that is an expert in the field?

I have a client that told me they had a friend that just got their license and they wanted to give them a chance to sell their home.   Have you heard this before?   

In this case, things fell apart when the inexperienced agent was verbally negotiating on his behalf.  Both parties seemingly had a deal worked out and the buyers went out of town for a long weekend. No due diligence was collected because a promise was made by the buyer's agent.  In the seller's mind his home was sold and he was moving forward with his plans.   His agent was telling people it was sold and interested buyers moved on.   Low and behold, buyers came back and changed their minds.   Numerous opportunities were lost as well as valuable time.   

An inexperienced agent keeps the facts below in mind at all times and is diligent throughout the transaction.   

Negotiations leading to a contract can be fast-paced, to the extent that brokers find themselves communicating offers and counter-offers, as well as acceptances, orally. An example of such a situation occurs when an oral counter-offer is communicated to the buyers, who orally agree to the new terms. The acceptance is orally relayed to the sellers, who now mistakenly think they have a valid contract.

The Statute of Frauds requires that all contracts for the sale of land or for lease agreements exceeding three years be in writing and signed by the parties to be enforceable. In order for a valid contract to exist, all negotiated terms must be in writing and signed by the parties. Any changes must also be in writing and initialed by the parties.


A broker can best keep his or her clients informed of all communications material to negotiations between the parties by ensuring that offers, counter-offers, and acceptances are in writing and contain all necessary signatures. Oral agreements for the sale of real property are not binding.

Thinking of selling and want a FREE Home evaluation?    Visit: Free Property Valuation (robyrobertson.com)

Friday, May 6, 2022

Birkdale | Huntersville | Charlotte|Lake Norman | Today’s Home Price Appreciation Is Great News for Existing Homeowners


Carolina Living Real Estate Never Charges More Than 4.5% to List and Sell Your Home

Today’s Home Price Appreciation Is Great News for Existing Homeowners | MyKCM

If you’re planning to sell your home this season, rising prices are great news for you. But it’s important to understand why prices are rising to begin with. One major factor is supply and demand.

In any industry, when there are more buyers for an item than there are of that item available, prices naturally rise. In those situations, buyers are willing to pay more to get the product or service they’re looking for when options are scarce. And that’s exactly what’s happening in the current real estate market.

Selma Hepp, Executive, Research & Insights and Deputy Chief Economist at CoreLogic, puts it like this:

With so few homes, buyers are once again left with fierce competition that’s driving the share of homes that sold over the listing price up to 66% . . . With the continued imbalance between supply and demand, home prices are likely to have another year of strong gains and are expected to average about 10% growth for the year.”

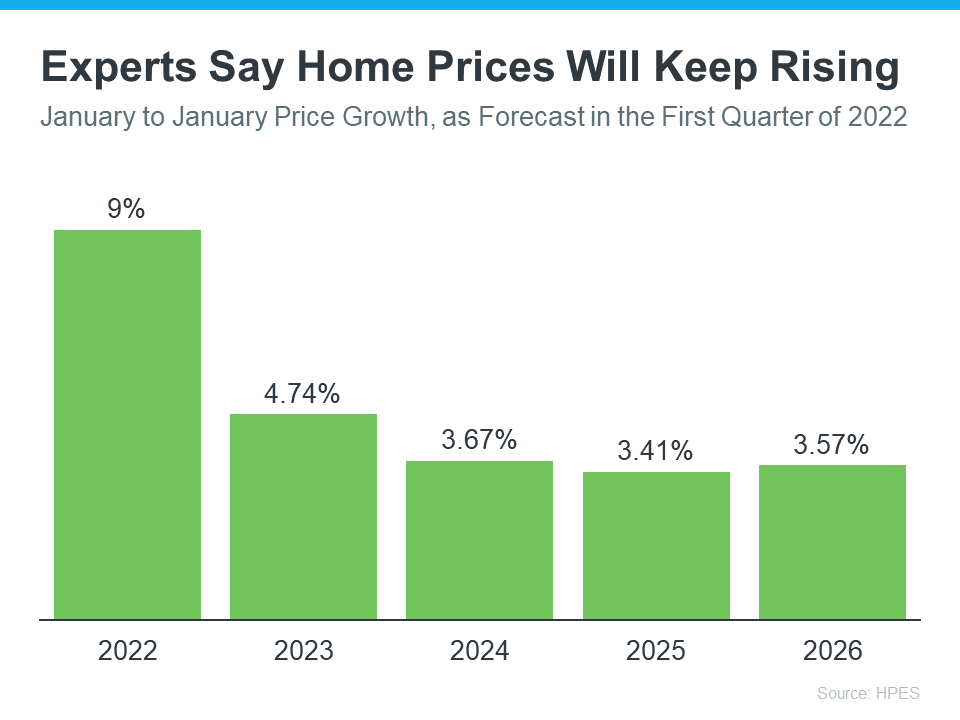
Because it will take some time for housing supply to increase, experts believe prices will continue rising. The latest Home Price Expectations Survey forecasts what will happen with home prices over the next 5 years. As the graph below shows, while the rate of appreciation will moderate over the next few years, prices will continue rising through 2026:

Today’s Home Price Appreciation Is Great News for Existing Homeowners | MyKCM

What This Means When You Sell Your House

If you’re a homeowner, the projection for continued price appreciation this year opens up an opportunity to move. That’s because it may give your equity a major boost. Equity is the difference between what you owe on your house and its market value. The amount of equity you have increases as you make your monthly payments and as rising home prices drive up the market value for your home.

Growing equity is a powerful tool for homeowners. When you sell your house, the equity you’ve built comes back to you in the sale. That money could be enough to cover some (if not all) of your down payment on your next home.

Of course, if you want to know how much equity you have in your current house, it’s crucial to work with a real estate professional. They follow current market trends and can help you understand your home’s value when you’re ready to sell.

What This Means for Your Next Purchase

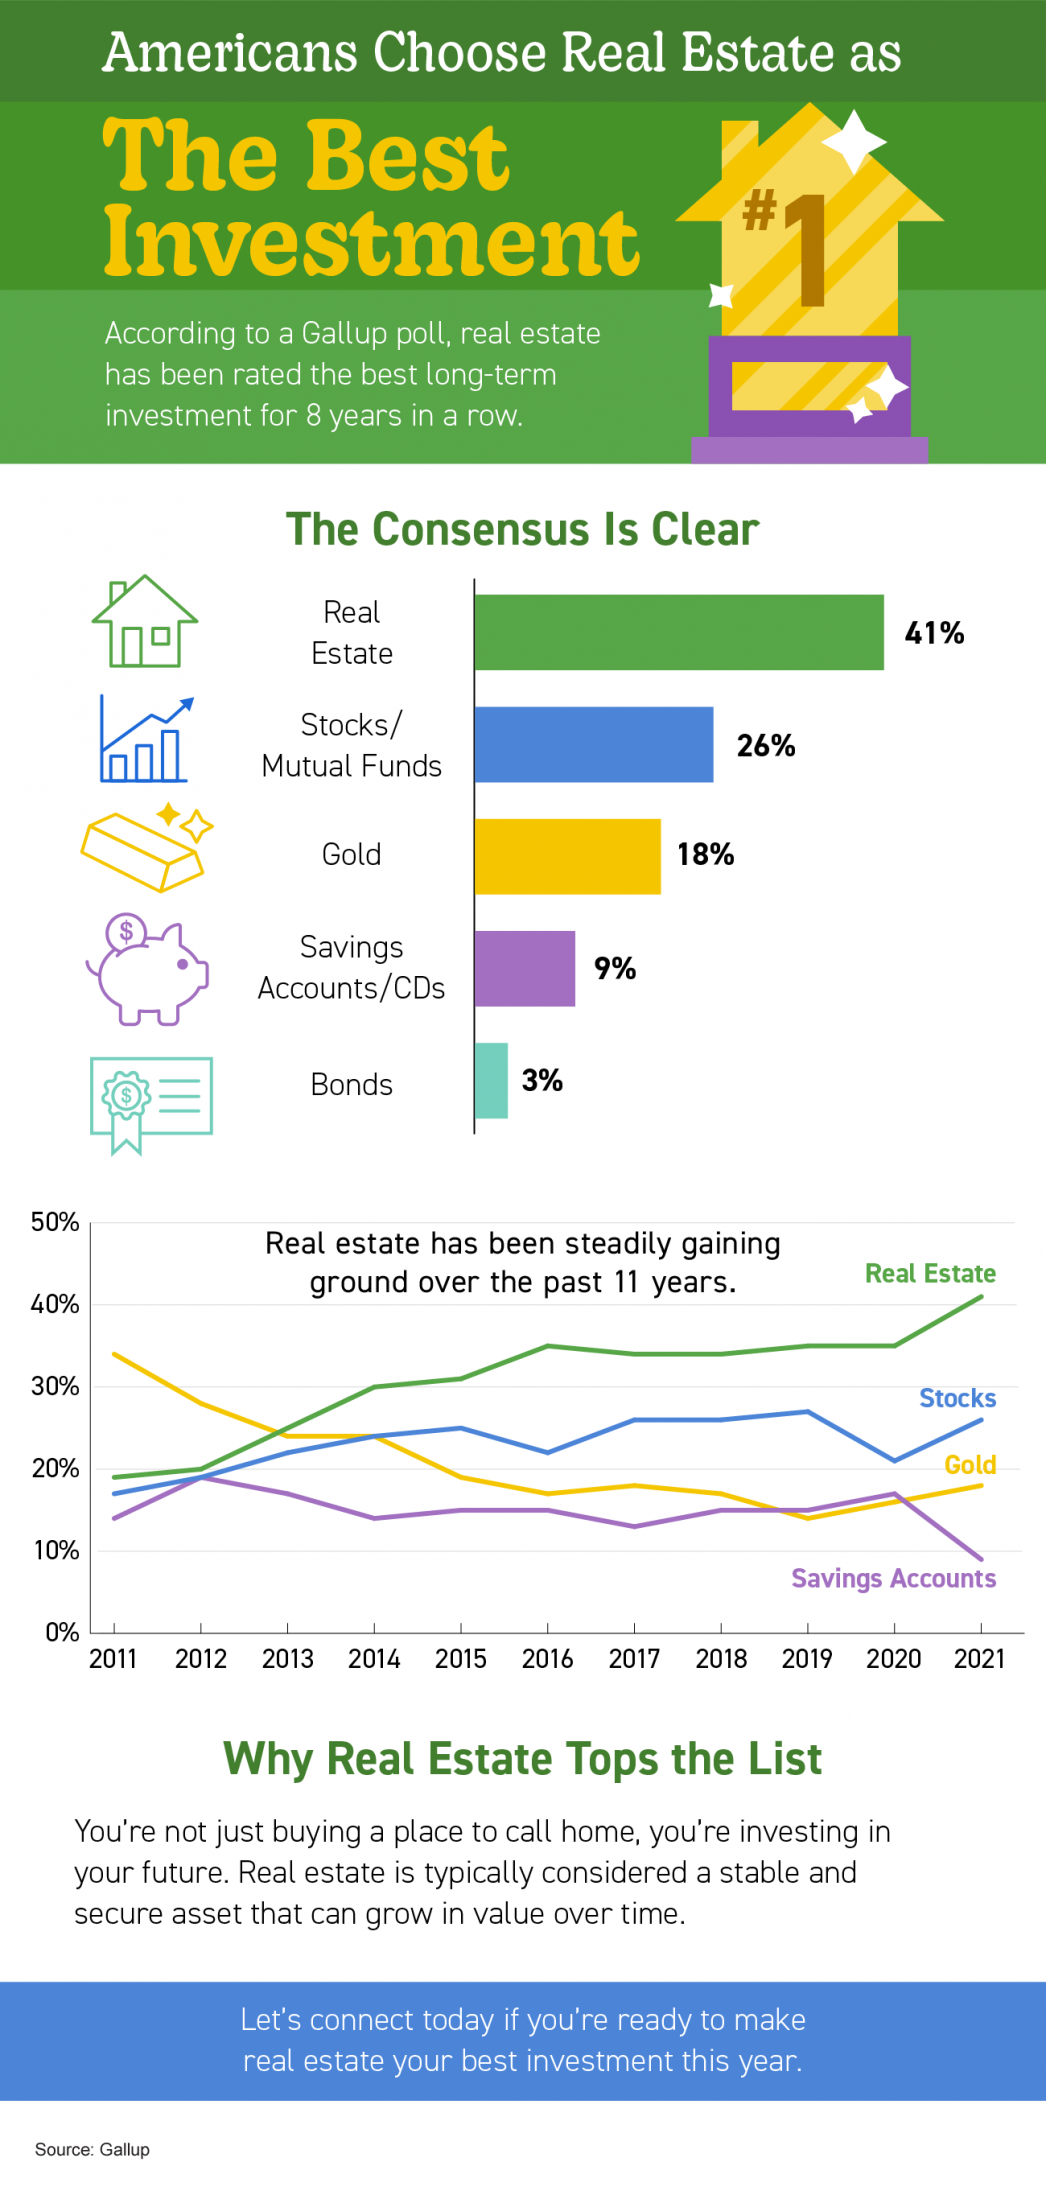
But today’s rising home values aren’t just good news if you’re ready to sell. Because price appreciation is forecast to continue in the years ahead, you can rest assured your next home will be an investment that should grow in value with time. That’s one of several reasons why real estate has been rated the best investment in a recent Gallup poll.

Bottom Line

If you’re weighing whether or not you should sell your house this season, know rising home values may be opening up an opportunity to use equity to fuel your move. Let’s connect so you can find out how much your home is worth and to learn more about all the benefits you have in today’s market.

Wednesday, April 13, 2022

Huntersville | Charlotte | Lake Norman : Thinking of Selling? How Much Equity Do You Have?


Do You Know How Much Equity You Have in Your Home? Let Carolina Living Real Estate Help You Figure It out!


Do You Know How Much Equity You Have in Your Home? [INFOGRAPHIC] | MyKCM

Some Highlights

  • If you’re a homeowner, your net worth has gotten a big boost. That’s because recent home price appreciation has increased your equity.
  • Your equity grows as you pay down your loan and as your home increases in value. Over the past year, the average homeowner’s equity grew by $55,300.
  • Ready to sell? Let’s connect to talk about how you can use that equity to fuel your next move.

Friday, April 8, 2022

Huntersville | Lake Norman | Charlotte: It’s Still a Sellers’ Market


Carolina Living Is Here to Help With This Chaotic Market!

It’s Still a Sellers’ Market [INFOGRAPHIC] | MyKCM

Some Highlights

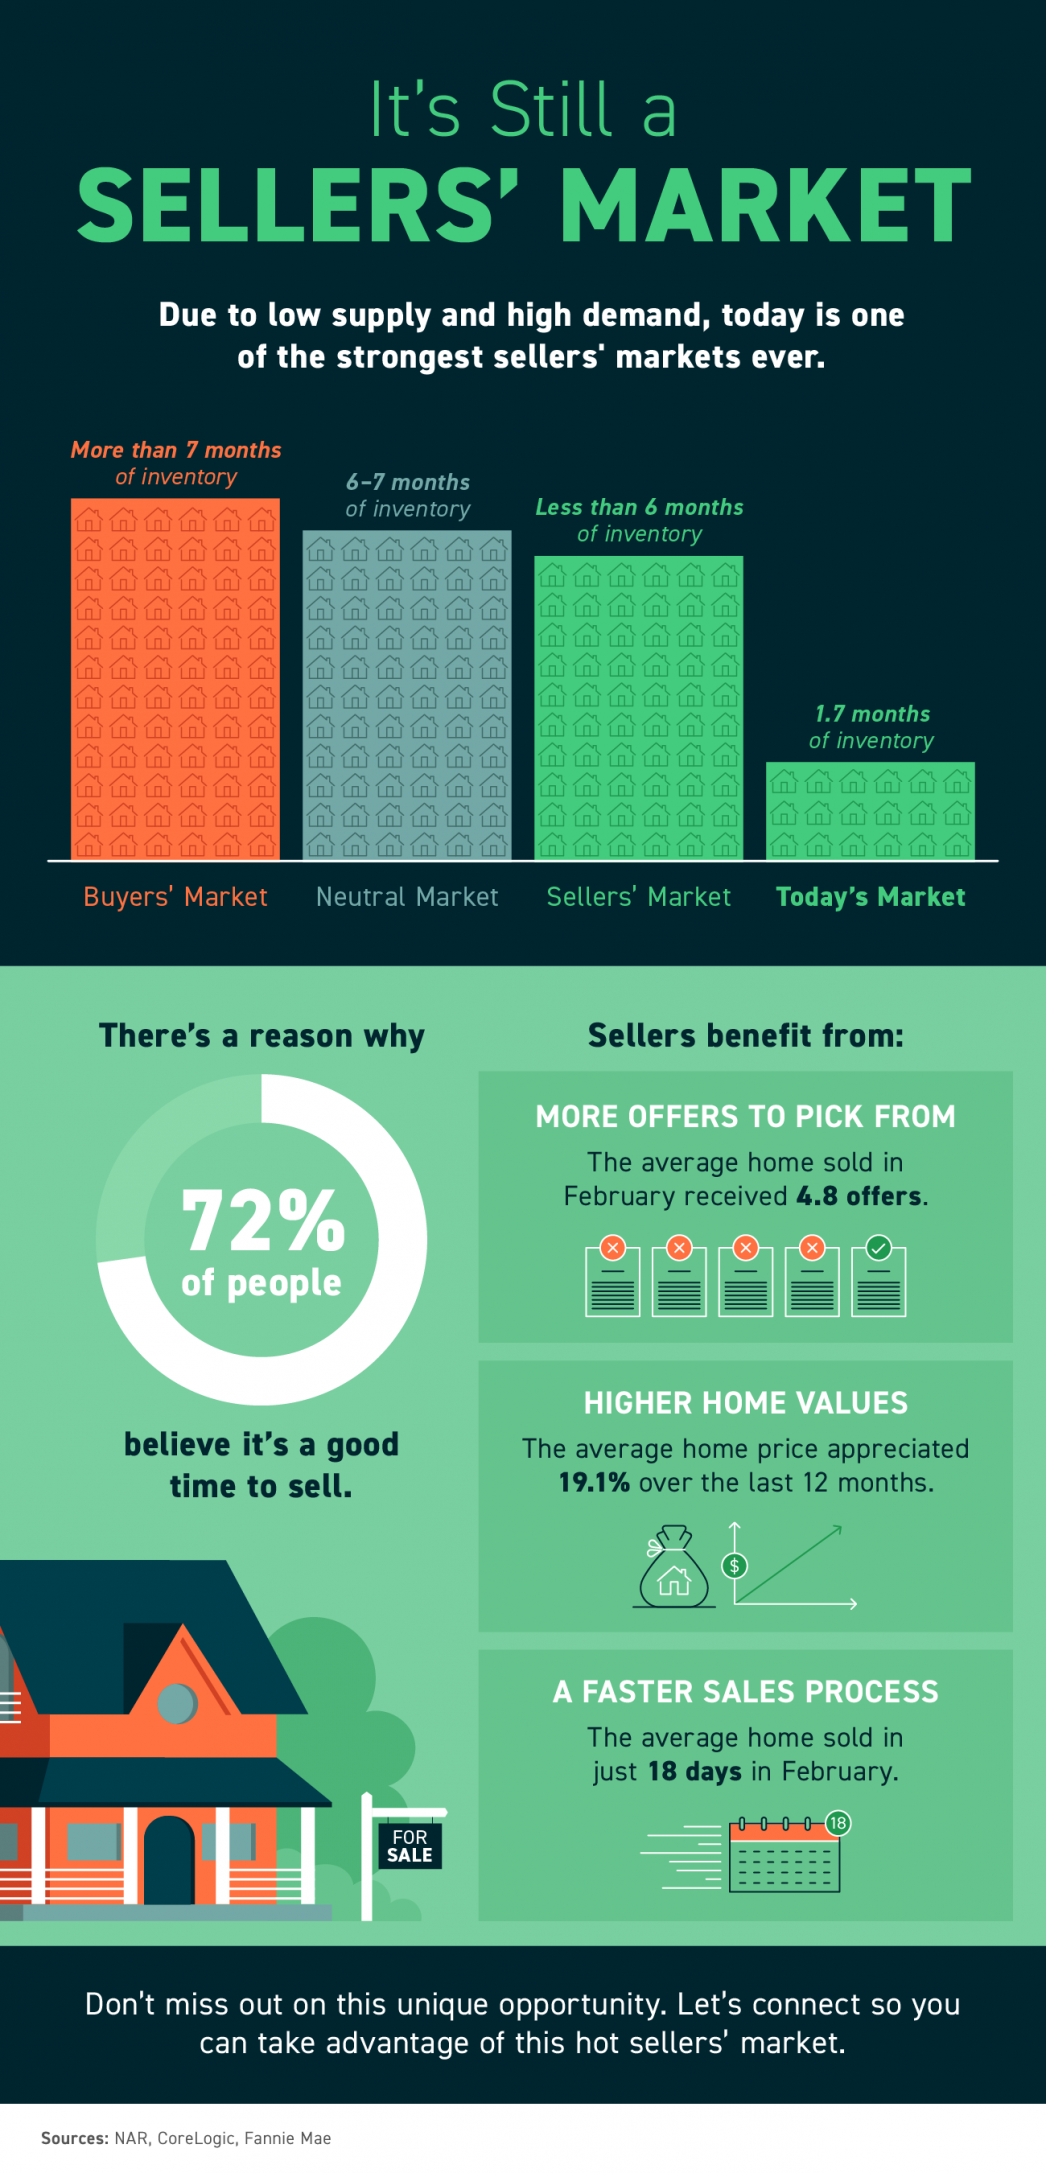
  • Due to low supply and high demand, today is one of the strongest sellers’ markets we’ve seen.
  • Sellers can benefit from more offers to pick from, higher home values, and a faster sales process. There’s a reason why 72% of people believe it’s a good time to sell.
  • Don’t miss out on this unique opportunity. Let’s connect so you can take advantage of this hot sellers’ market.

Tuesday, February 8, 2022

Huntersville, Charlotte, Lake Norman | Why Right Now Is a Once-in-a-Lifetime Opportunity for Sellers


Why Right Now Is a Once-in-a-Lifetime Opportunity for Sellers | MyKCM

If you’re thinking about selling your house in 2022, you truly have a once-in-a-lifetime opportunity at your fingertips. When selling anything, you always hope for strong demand for the item coupled with a limited supply. That maximizes your leverage when you’re negotiating the sale. Home sellers are in that exact situation right now. Here’s why.

Demand Is Very Strong

According to the latest Existing Home Sales Report from the National Association of Realtors (NAR), 6.18 million homes were sold in 2021. This was the largest number of home sales in 15 years. Lawrence Yun, Chief Economist for NAR, explains:

“Sales for the entire year finished strong, reaching the highest annual level since 2006. . . . With mortgage rates expected to rise in 2022, it's likely that a portion of December buyers were intent on avoiding the inevitable rate increases.”

Demand isn’t expected to weaken this year, either. In addition, the Mortgage Finance Forecast, published last week by the Mortgage Bankers’ Association (MBA), calls for existing-home sales to reach 6.4 million homes this year.

Supply Is Very Limited

The same sales report from NAR also reveals the months’ supply of inventory just hit the lowest number of the century. It notes:

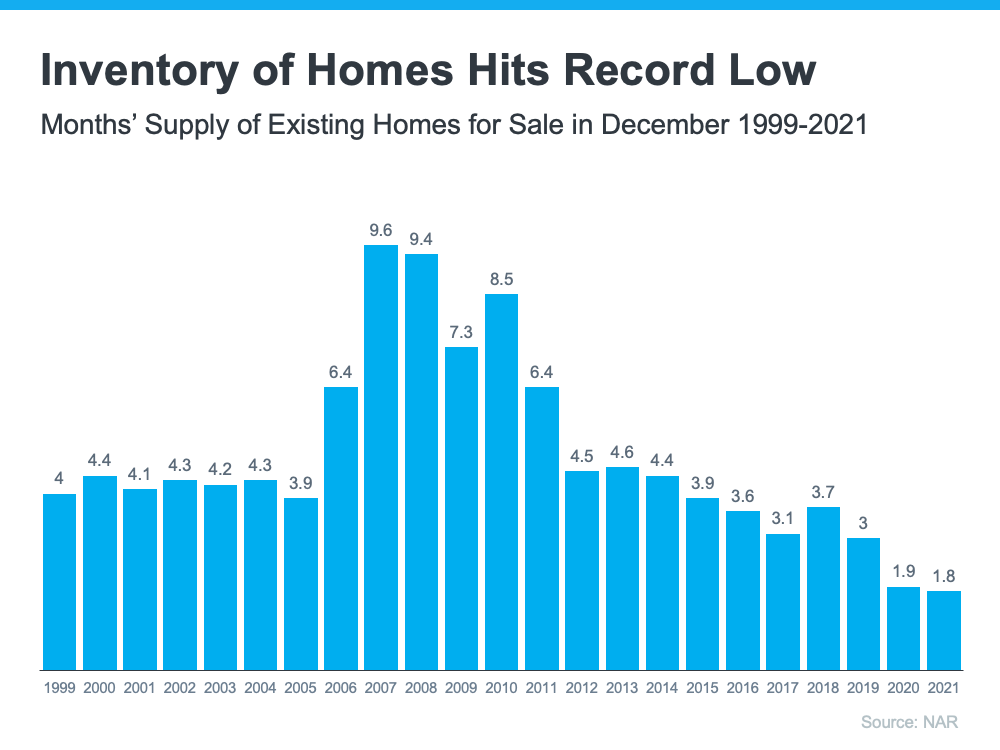
“Total housing inventory at the end of December amounted to 910,000 units, down 18% from November and down 14.2% from one year ago (1.06 million). Unsold inventory sits at a 1.8-month supply at the present sales pace, down from 2.1 months in November and from 1.9 months in December 2020.”

The reality is, inventory decreases every year in December. That’s just how the typical seasonal trend goes in real estate. However, the following graph emphasizes how this December was lower than any other December going all the way back to 1999.

Why Right Now Is a Once-in-a-Lifetime Opportunity for Sellers | MyKCM

Right Now, Sellers Have Maximum Leverage

As mentioned above, when there’s strong demand for an item and a limited supply of it available, the seller has maximum leverage in the negotiation. In the case of homeowners who are thinking about selling, there may never be a better time than right now. While demand is this high and inventory is this low, you’ll have leverage in all aspects of the sale of your house.

Today’s buyers know they need to be flexible negotiators that make very competitive offers, so here are a few areas that could tip in your favor when your house goes on the market:

  • Competitive sales price
  • Flexible closing date
  • Potential for a leaseback to allow you more time to find a home
  • Minimal offer contingencies

Bottom Line

If you’re thinking of selling your house this year, now is the optimal time to list it. Let’s connect to discuss how you can put your house on the market today.

Wednesday, January 26, 2022

What Does The Coming Year Hold For Housing Market?

What does the coming year hold for the housing market? Mortgage rates are projected to rise, and so are home prices. Experts forecast buyer demand will remain strong as people try to capitalize on rates and prices before they climb. DM Carolina Living Real Estate today if you’re ready to buy or sell so you can make your best move in the new year.


Friday, January 21, 2022

Huntersville Chooses Real Estate as the Best Investment


 Carolina Living Real Estate Is Here For You

Americans Choose Real Estate as the Best Investment [INFOGRAPHIC] | MyKCM

Some Highlights

  • According to a Gallup poll, real estate has been rated the best long-term investment for eight years in a row.
  • Real estate tops the list because you’re not just buying a place to call home – you’re investing in your future. Real estate is typically considered a stable and secure asset that can grow in value over time.
  • Let’s connect today if you’re ready to make real estate your best investment this year.

Wednesday, January 19, 2022

Huntersville Sellers: Don’t Wait Until Spring To Make Your Move


Carolina Living Real Estate and Roby Robertson saves you money!

Sellers: Don’t Wait Until Spring To Make Your Move | MyKCM

As you plan out your goals for the year, moving up to your dream home may top the list. But, how do you know when to make your move? You want to time it just right so you can get the most out of the sale of your current house. You also want to know you’re making a good investment when you buy your new home. What you may not realize is, that opportunity to get the best of both worlds is already here.

You don’t want to wait until spring to spring into action. The current market conditions make this winter an ideal time to move. Here’s why.

1. The Number of Homes on the Market Is Still Low

Today’s limited supply of houses for sale is putting sellers in the driver’s seat. There are far more buyers in the market than there are homes available, and that means buyers are eagerly waiting for your house. Listing your house now makes it the center of attention. As a seller, that means when it’s priced correctly, you can expect it to sell quickly and get multiple strong offers this season. Just remember, experts project more inventory will come to market as we move through the winter months. The realtor.com 2022 forecast says this:

“After years of declining, the inventory of homes for sale is finally expected to rebound from all-time lows.”

Selling now may help you maximize the return on your investment before your house has to face more competition from other sellers.

2. Your Equity Is Growing in Record Amounts

Current homeowners are sitting on record amounts of equity thanks to today’s home price appreciation. According to the latest report from CoreLogicthe average homeowner gained $56,700 in equity over the past 12 months.

That much equity can open doors for you to make a move. If you’ve been holding off on selling because you’re worried about how rising prices will impact your own home search, rest assured your equity can help fuel your next move. It may be just what you need to cover a large portion – if not all – of the down payment on your next purchase.

3. While Rising, Mortgage Rates Are Still Historically Low

In January of last year, mortgage rates hit the lowest point ever recorded. Today, rates are starting to rise, but that doesn’t mean you’ve missed out on locking in a low rate. Current mortgage rates are still far below what they’ve been in recent decades:

  • In the 2000s, the average mortgage rate was 6.27%
  • In the 1990s, the average rate was 8.12%

Even with mortgage rates rising above 3%, they’re still worth taking advantage of. You just want to do so sooner rather than later. Experts are projecting rates will continue to rise throughout this year, and when they do, it’ll cost you more to purchase your next home.

4. Home Prices Are Going To Keep Rising with Time

According to industry leaders, home prices will also continue appreciating this year. While experts are forecasting more moderate home price growth than last year, it’s important to note prices will still be moving in an upward direction throughout 2022.

What does that mean for you? If you’re selling so you can move into a bigger home or downsize to the home of your dreams, you want to consider moving now before rates and prices rise further. If you’re ready, you have an opportunity to get ahead of the curve by purchasing your next home before rates and prices climb higher.

Bottom Line

If you’re considering selling to move up or downsize, this may be your moment, especially with today’s low mortgage rates and limited inventory. Let’s connect today to get set up for homebuying success this year.

Tuesday, January 11, 2022

Huntersville | Charlotte | Lake Norman : Why Inflation Shouldn’t Stop You from Buying a Home in 2022

 Let Carolina Living Real Estate Help

Why Inflation Shouldn’t Stop You from Buying a Home in 2022 | MyKCM


If you’re following along with the news today, you’re probably hearing a lot about record-breaking home prices, rising consumer costs, supply chain constraints, and more. And if you’re thinking about purchasing a home this year, all of these inflationary concerns are likely making you wonder if you should wait to buy. Investopedia explains that during a period of high inflation, prices rise across the board. And while home prices aren’t immune from this increase, here’s why inflation shouldn’t stop you from buying a home in 2022.

Homeownership Offers Stability and Security

Home prices have been increasing for quite some time, and experts say they’re going to continue to climb throughout 2022. So, as a buyer, how can you protect yourself from rising costs for things like food, shelter, entertainment, and other goods and services? The answer lies in housing.

Buying a home allows you to lock in your monthly mortgage payment for the foreseeable future. That means as other prices rise, your monthly payment will be consistent thanks to your fixed-rate mortgage. This gives you the peace of mind that the bulk of your housing costs is shielded from inflation.

James Royal, Senior Wealth Management Reporter at Bankrate, says:

A fixed-rate mortgage allows you to maintain the biggest portion of housing expenses at the same payment. Sure, property taxes will rise and other expenses may creep up, but your monthly housing payment remains the same.”

If you rent, you don’t have that same benefit and you won’t be protected from rising housing costs. As an added incentive to buy, consider that today’s mortgage interest rates are lower than they have been in decades. While inflation decreases what your dollars can buy, low mortgage rates help counteract it by boosting your purchasing power so you can get more home for your money. They also help keep your monthly payments down. This is especially important during an inflationary period because you’ll want to protect yourself from the impact of inflation as much as possible.

Ali Wolf, Chief Economist at Zondaexplains:

“If you have cash and are expecting inflation, you want to think through where you can put your money so it does not lose value. Housing is commonly looked at as a good inflation hedge, especially with interest rates so low.”

Bottom Line

The best hedge against inflation is a fixed housing cost. That’s why you shouldn’t let it stop you from buying a home this year. Not sure where to start? Let’s connect so you have expert advice and help throughout every step of the homebuying process.

Thursday, January 6, 2022

Huntersville| There Won’t Be a Wave of Foreclosures in the Housing Market


Carolina Living Real Estate Is Here For You

There Won’t Be a Wave of Foreclosures in the Housing Market | MyKCM

When mortgage forbearance plans were first announced and the pandemic surged through the country in early 2020, many homeowners were allowed to pause their mortgage payments. Some analysts were concerned that once the forbearance program ended, the housing market would experience a wave of foreclosures like what happened after the housing bubble 15 years ago.

Here’s a look at why that isn’t the case.

1. There Are Fewer Homeowners in Trouble This Time

After the last housing crash, over nine million households lost their homes to a foreclosure, short sale, or because they gave it back to the bank. Many believed millions of homeowners would face the same fate again this time.

However, today’s data shows that most homeowners exited their forbearance plan either fully caught up on payments or with a plan from the bank that restructured their loan in a way that allowed them to start making payments again. The latest data from the Mortgage Bankers Association (MBA) studies how people exited the forbearance program from June 2020 to November 2021.

Here are those findings:

38.6% left the program paid in full
  • 19.9% made their monthly payments during the forbearance period
  • 11.8% made up all past-due payments
  • 6.9% paid off the loan in full
44% negotiated work-out repayment plans
  • 29.1% received a loan deferral
  • 14.1% received a loan modification
  • 0.8% arranged a different repayment plan
0.6% sold as a short sale or did a deed-in-lieu
16.8% left the program still in trouble and without a loss mitigation plan in place

2. Those Left in the Program Can Still Negotiate a Repayment Plan

As of last Friday, the total number of mortgages still in forbearance stood at 890,000. Those who remain in forbearance still have the chance to work out a suitable plan with the servicing company that represents their lender. And the servicing companies are under pressure to do just that by both federal and state agencies.

Rick Sharga, Executive Vice President at RealtyTrac, says in a recent tweet:

“The [Consumer Financial Protection Bureau] and state [Attorneys General] look like they're adopting a ‘zero tolerance’ approach to mortgage servicing enforcement. Likely that this will limit #foreclosure activity for a good part of 2022, while servicers explore all possible loss [mitigation] options.”

For more information, read the warning issued by the Attorney General of New York State.

3. Most Homeowners Have More Than Enough Equity To Sell Their Homes

For those who can’t negotiate a solution and the 16.8% who left the forbearance program without a work-out, many will have enough equity to sell their homes and leave the closing with cash instead of facing foreclosures.

Due to rapidly rising home prices over the last two years, the average homeowner has gained record amounts of equity in their home. As Frank Martell, President & CEO of CoreLogic, explains:

“Not only have equity gains helped homeowners more seamlessly transition out of forbearance and avoid a distressed sale, but they’ve also enabled many to continue building their wealth.”

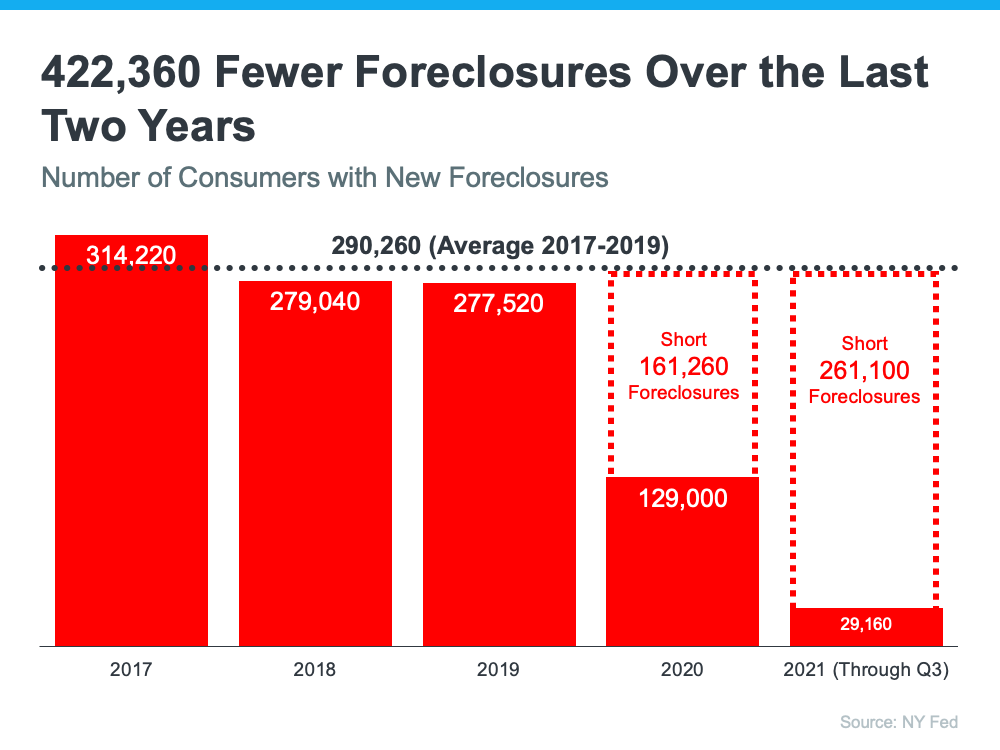
4. There Have Been Far Fewer Foreclosures Over the Last Two Years

One of the seldom-reported benefits of the forbearance program was that it allowed households experiencing financial difficulties prior to the pandemic to enter the program. It gave those homeowners an extra two years to get their finances in order and work out a plan with their lender. That prevented over 400,000 foreclosures that normally would have come to the market had the new forbearance program not been available. Otherwise, the real estate market would have had to absorb those foreclosures. Here’s a graph depicting this data:

There Won’t Be a Wave of Foreclosures in the Housing Market | MyKCM

5. The Current Market Can Easily Absorb Over a Million New Listings

When foreclosures hit the market in 2008, they added to the oversupply of houses that were already for sale. That resulted in over a nine-month supply of listings, and anything over a six-month supply can cause prices to depreciate.

It’s exactly the opposite today. The latest Existing Home Sales Report from the National Association of Realtors (NAR) reveals:

“Total housing inventory at the end of November amounted to 1.11 million units, down 9.8% from October and down 13.3% from one year ago (1.28 million). Unsold inventory sits at a 2.1-month supply at the current sales pace, a decline from both the prior month and from one year ago.”

A balanced market would have approximately a six-month supply of inventory. At 2.1 months, the market is severely understocked. Even if one million homes enter the market, there still won’t be enough inventory to meet the current demand.

Bottom Line

The end of the forbearance plan will not cause any upheaval in the housing market. Sharga puts it best:

“The fact that foreclosure starts declined despite hundreds of thousands of borrowers exiting the CARES Act mortgage forbearance program over the last few months is very encouraging. It suggests that the ‘forbearance equals foreclosure’ narrative was incorrect. . . .”

Wednesday, December 22, 2021

Huntersville | What Everyone Wants To Know: Will Home Prices Decline in 2022?


Merry Christmas From Carolina Living Real Estate

What Everyone Wants To Know: Will Home Prices Decline in 2022? | MyKCM

If you’re thinking of buying a home in today’s housing market, you may be wondering how strong your investment will be. You might be asking yourself: if I buy a home now, will it lose value? Or will it continue to appreciate going forward? The good news is, according to the experts, home prices are not projected to decline. Here’s why.

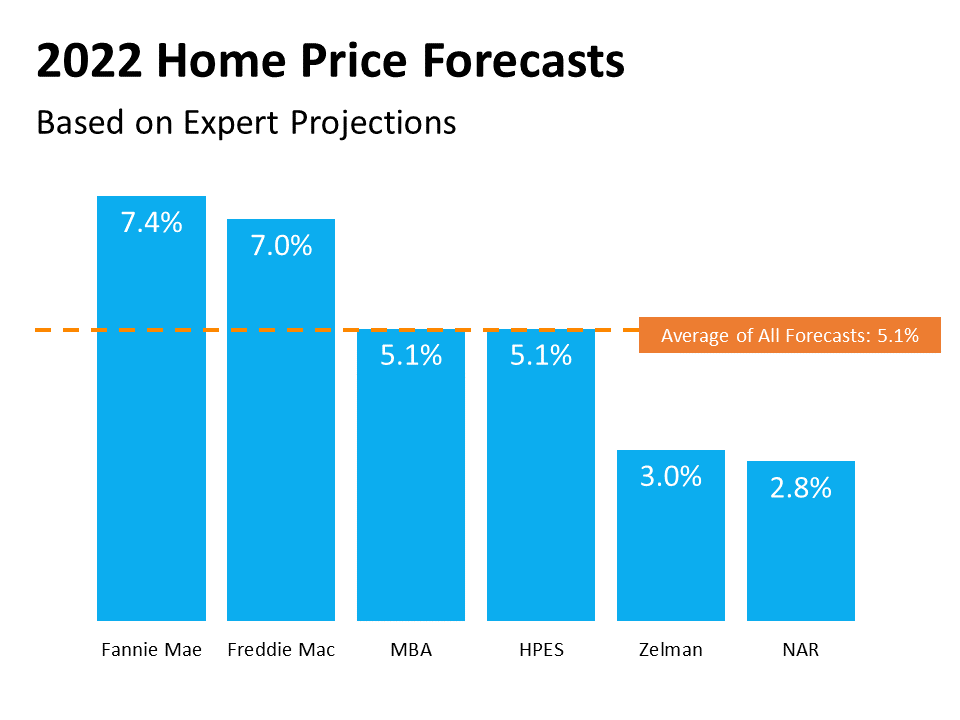
With buyers still outweighing sellers, home prices are forecast to continue climbing in 2022, just at a slower or more moderate pace. Why the continued increase? It’s the simple law of supply and demand. When there are fewer items on the market than there are buyers, the competition for that item makes prices naturally rise.

And while the number of homes for sale today is expected to improve with more sellers getting ready to list their houses this winter, we’re certainly not out of the inventory woods yet. Thus, the projections show continued appreciation, but at a more moderate rate than what we’ve seen over the past year.

Here’s a look at the latest 2022 expert forecasts on home price appreciation:What Everyone Wants To Know: Will Home Prices Decline in 2022? | MyKCMWhat’s the biggest takeaway from this graph? None of the major experts are projecting depreciation in 2022. They’re all showing an increase in home prices next year.

And here’s what some of the industry’s experts say about how that will play out in the housing market next year:

Brad Hunter of Hunter Housing Economics explains:

“. . . the recent unsustainable rate of home price appreciation will slow sharply. . . . home prices will not decline. . . but they will simply rise at a more sustainable pace.”

Danielle Hale from realtor.com agrees:

Price growth is expected to move back toward a normal range, but this is on top of recent high prices, . . . So prices will [still] hit new highs. . . . The pace of price growth is going to slow notably . . . ”

What Does This Mean for the Housing Market?

While home price appreciation is expected to continue, it isn’t projected to be the record-breaking 18 to almost 20% increase the market saw over the past 12 months. Overall, it’s important to note that price increases won’t be as monumental as they were in 2021 – but they certainly won’t decline anytime soon.

What Does That Mean for You?

With motivated buyers in the market and so few homes available to purchase, the imbalance of supply and demand will continue to put upward pressure on home prices in 2022. And when home price appreciation is in the forecast, that’s a clear indication your investment in homeownership is a sound one.

Bottom Line

It’s important to know that home prices are not projected to decline in the new year. Instead, they’re forecast to rise, just at a more moderate pace. Let’s connect to make sure you’re up to date on what’s happening with home price appreciation in our market, so you can make an informed decision about your next move.

Birkdale |Lake Norman|Charlotte = Your Realtor For Life - Roby Robertson

Contact Info Mobile 704 451 7051] Email carolinalivingrealestate@yahoo.com    **Professional Summary**   Licensed real estate professional w...